SEPTEMBER 2026 – GHANA
INCOME TAX (AMENDMENT) ACT, 2026
It is important that employers note the following:
President assents to income tax changes
Ghanaian President John Dramani Mahama has assented to the Income Tax (Amendment) Act, 2026 on 26 August 2026. The amendment revises the graduated income tax bands for resident individuals.
Revised resident individual tax bands:
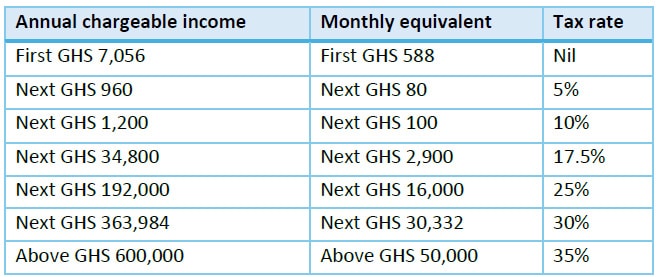
The annual nil-rate band increases from GHS 5,880 to GHS 7,056. The new monthly threshold of GHS 588 broadly reflects the rounded monthly equivalent of the 2026 National Daily Minimum Wage of GHS 21.77, based on a 27-day working month. The minimum wage has been in effect since 1 January 2026.
Although the policy objective of exempting minimum wage earnings from income tax is consistent with Government’s broader tax relief agenda, the specific resident individual tax bands ultimately enacted in the Income Tax (Amendment) Act, 2026 do not appear to have been detailed in the 2026 Budget Speech. Instead, they were introduced later through the Income Tax (Amendment) Bill, 2026.
Payroll implications
Employers should review and update payroll systems to accommodate the new resident PAYE table.
Based on the published amendment, the following areas do not appear to have been changed:
- The 25% tax rate generally applicable to non-resident individuals.
- The special tax treatment applicable to qualifying employee bonuses.
- Overtime taxation rules for qualifying junior employees.
- The 5% withholding tax treatment applicable to casual workers.
- SSNIT (Social Security and National Insurance Trust) contribution rates.
Effective date: not yet confirmed
While presidential assent was granted on 26 August 2026, the effective date for payroll implementation remains unclear.
Article 106(11) of Ghana’s Constitution provides that an assented bill does not come into force unless it has been published in the Gazette. Unless the Act specifies another commencement date, the expected legal commencement date is therefore the date on which the enacted Act is published in the Gazette, not necessarily the 26 August assent date confirmed by the Presidency of Ghana announcement.
Employer action
Employers should:
- Prepare payroll systems for the revised resident PAYE bands.
- Monitor for publication of the Act in the Gazette and for any GRA implementation guidance.
- Obtain confirmation of the commencement date before applying the new tax table or making retrospective payroll adjustments.
To download and view the Income Tax (Amendment) Bill, 2026, follow the link.